Rental Property Investing (2026): The Complete Beginner’s Guide to Buying, Financing, and Profiting from Rentals
Rental property investing is buying residential real estate — a single-family home, duplex, or small multifamily — and renting it to tenants for monthly income. Investors profit four ways: cash flow (rent minus all expenses), principal paydown (tenant-funded equity), appreciation (property value growth), and tax benefits (depreciation, deductions, and 1031 Exchanges).
Rental property investing means buying residential real estate to rent to tenants, creating monthly cash flow while building equity through mortgage paydown and long-term appreciation. Done well, it’s one of the more reliable ways to build wealth in the U.S. Done carelessly — with soft math and no reserves — it’s one of the faster ways to lose a down payment.
This guide is the 2026-ready version: how rentals actually make money, the numbers that have to clear before you buy, financing routes that fit your situation, a repeatable market-selection process, and the landlord systems that protect your returns after closing. Every calculation here can be run directly in so you’re not doing this math on a napkin.
How Rental Properties Actually Make Money
Most beginners judge a rental on cash flow alone, then get confused when experienced investors buy deals with thin monthly cash flow. That’s because cash flow is only one of four return streams.
Cash Flow (the Only Spendable Return)
Cash flow is rent minus every expense — including the ones that don’t bill monthly, like maintenance, capex reserves, vacancy, and management. It’s the number that shows up in your bank account, and the one that keeps you solvent when a furnace dies in January.
Principal Paydown (Tenant-Funded Equity)
Each mortgage payment converts a small slice of debt into equity. You never see this money — it’s invisible until you sell or refinance — but on a 30-year amortizing loan it’s a meaningful share of your total return, and the tenant is funding it.
Appreciation (Bonus, Not a Plan)
Appreciation is the property becoming worth more over time. It’s real, and historically it has added significantly to investor returns — but it’s entirely outside your control. Treat it as a bonus you didn’t underwrite, never as the reason a deal works.
Tax Treatment
Depreciation lets you deduct a portion of the building’s value against rental income every year, which is why a property can throw off positive cash flow and a paper loss at the same time. You can also deduct mortgage interest, property taxes, insurance, repairs, and management fees, and a 1031 exchange lets you defer capital gains tax when you sell and roll the proceeds into another property. (Depreciation and 1031 rules are set by the IRS — see irs.gov for current guidance, and confirm anything state-specific with a licensed CPA, since state tax treatment varies.)
2026 Reality Check: What’s Changed and What Still Works
Higher borrowing costs, rising insurance premiums, and local property tax reassessments have tightened cash flow in many markets over the last few years. Deals still work — the bar to clear is just higher than it was.
| Factor | 2026 Pressure Point | What It Means for You |
| Interest rates | Investment loans typically run 0.5–1% above owner-occupied rates | Lower cash flow per dollar borrowed than a few years ago |
| Insurance | 0.5–1.5% of property value annually, rising fastest in coastal and wildfire-exposed markets | Get a real quote before you underwrite, not a national average |
| Property taxes | Many jurisdictions reassess value at sale | Your tax bill in year one may be higher than the seller’s last bill |
| Underwriting bar | Lenders and investors expect thicker margins | Marginal deals from 2021 don’t clear anymore |
Minimum thresholds worth using as guardrails, not gospel:
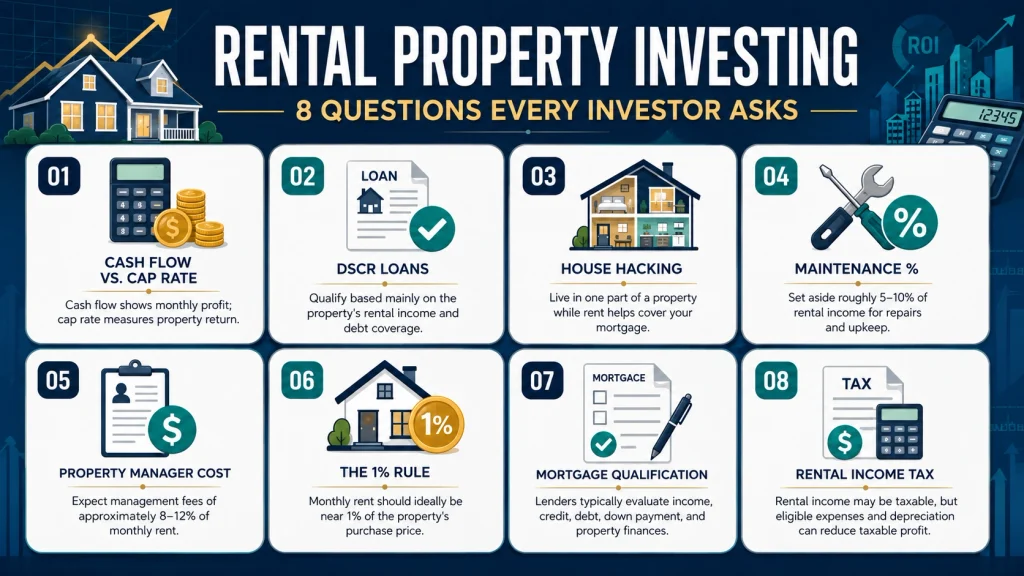
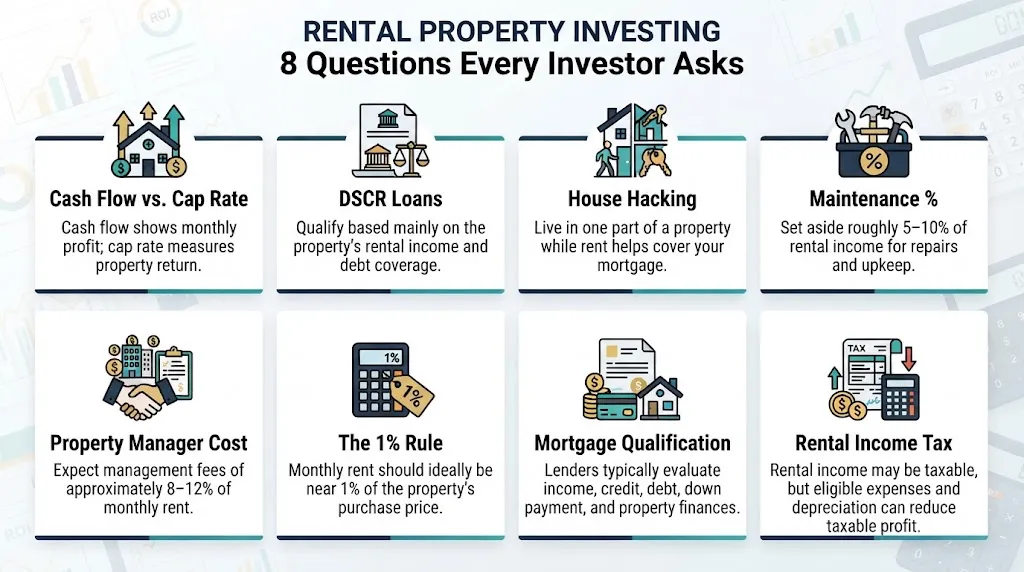
- DSCR of 1.20–1.25 or higher (Net Operating Income ÷ debt service) signals healthy coverage.
- Cap rate that beats your borrowing cost by at least 1–2 percentage points in your target asset class.
- Operating expenses modeled at 40–50% of gross rental income for small residential rentals, once you include vacancy and capex — not just the mortgage, taxes, and insurance.
Are You Financially Ready? (Checklist + Numbers)
Before you shop for a property, confirm you can fund and sustain one without it becoming a source of stress.
| Requirement | Typical Range (2026) |
| Down payment | 15–25% (20–25% most common for standard investment loans) |
| Credit score | 680+ generally required; 720+ gets the best pricing |
| Debt-to-income (DTI) | Below 36–43% including the new payment; lenders often count only ~75% of projected rent |
| Reserves | 3–6 months of full property expenses per property, beyond your personal emergency fund |
Run your own stress test: model a 10% rent decline stacked with two months of vacancy. If that combination makes the deal insolvent, it’s thinner than it looks on the listing page. This is exactly the kind of scenario Calclandlord’s cash flow calculator is built to run in seconds.
Choose Your Strategy (Match the Asset to Your Goal)
Your best first deal depends on your available capital, risk tolerance, and how hands-on you want to be — not on whichever strategy is trending.
| Strategy | Entry Cost | Hands-On Level | Best For |
| House hacking | Lowest (owner-occupant financing) | Highest — you live there | Investors with limited capital, comfortable sharing a property |
| Single-family rental (SFR) | Moderate | Low–moderate | Simplicity, easier resale, longer-tenure tenants |
| Small multifamily (2–4 units) | Moderate–higher | Moderate | Vacancy diversification, more units per closing |
| Mid-term / short-term rental | Varies | Highest — active operations | Investors wanting higher gross income and comfortable with volatility |
House Hacking
Live in one unit of a small multifamily, or rent rooms in a single-family home, and finance it as a primary residence to unlock lower down payments and better rates. The trade-off is obvious: you live inside your investment.
Single-Family Rentals
Easier to finance and easier to sell later. They tend to attract longer-tenure tenants — but one vacancy means 100% income loss until you re-rent.
Small Multifamily (2–4 Units)
More units per transaction and better vacancy diversification: one empty unit out of four is a dent, not a disaster. Financing and hands-on management are both a step up in complexity from a single-family home.
Mid-Term and Short-Term Rentals
Higher gross rents are possible, but income fluctuates with travel demand, and local short-term rental ordinances can change the math (or the legality) overnight. Operations are meaningfully more intensive than a standard lease.
Pick a Market You Can Underwrite (Step-by-Step)
Location is the one variable you can’t renovate your way out of. Use a repeatable process instead of “look up crime and schools” advice.
- Top-down filters. Screen metros and counties on employment trends, population and household growth, and rent-to-price ratio. Look at the new-supply pipeline — a wave of new construction can suppress rent growth for years.
- Neighborhood screens. Narrow to specific neighborhoods using school ratings, crime trends, commute times, transit access, and local landlord-tenant regulations and eviction timelines (these vary enormously by state and city).
- Rent comps and expense benchmarks. Pull active and recently-leased comps to set a realistic rent estimate, and gather actual local numbers for property taxes, insurance, and typical maintenance costs — not national averages.
Public sources worth starting with: local MLS/rent comp data, HUD Fair Market Rent data, and your state or county assessor’s site for property tax history.
Explore More: https://calclandlord.com/property-investment-returns/
Analyze Any Deal Without Getting Burned
The difference between a good investment and a costly mistake almost always comes down to whether the expense stack was modeled honestly.
The Full Expense Stack
Model all of these — not just the mortgage:
- Property taxes — check local reassessment rules; your bill may jump after purchase
- Insurance — 0.5–1.5% of value, higher and rising in exposed regions
- Property management — 8–10% of rent, count it even if you plan to self-manage
- Maintenance — 5–10% of rent, higher on older properties
- Capital expenditure reserve — 5–10% of rent for roof, HVAC, water heater, and other big-ticket replacements
- Vacancy — 5–8% of rent; even great tenants eventually leave
Metrics That Matter
| Metric | Formula | What It Tells You |
| Cash-on-cash return | Annual pre-tax cash flow ÷ cash invested | Return on the actual money you put in |
| Cap rate | NOI ÷ purchase price | Financing-agnostic comparison across deals |
| DSCR | NOI ÷ annual debt service | Whether the property covers its own loan (below 1.0 = it can’t) |
| GRM | Purchase price ÷ gross annual rent | Quick, rough screening tool |
| Operating expense ratio | Operating expenses ÷ gross income | Sanity check on how much rent survives to the bottom line |
Worked Example: From Listing to Decision
The listing: A $310,000 single-family rental, 20% down ($62,000), renting for $2,400/month.
| Line Item | Monthly | Annual |
| Gross rent | $2,400 | $28,800 |
| Vacancy (6%) | –$144 | –$1,728 |
| Property management (9%) | –$216 | –$2,592 |
| Maintenance (7%) | –$168 | –$2,016 |
| Capex reserve (7%) | –$168 | –$2,016 |
| Property taxes | –$258 | –$3,100 |
| Insurance | –$150 | –$1,800 |
| Net Operating Income (NOI) | $1,296 | $15,548 |
| Debt service (7% rate, 30-yr, $248,000 loan) | –$1,650 | –$19,800 |
| Cash flow | –$354 | –$4,252 |
Base case verdict: negative cash flow — this deal doesn’t clear as written. Before walking away, check the break-even rent: the minimum rent needed to cover every expense line and the debt service. Here, that’s roughly $2,754/month (NOI expenses + debt service, grossed back up for the percentage-of-rent items) — about $354 above the current rent. If comps support $2,750+, this could work with a rent increase at the next lease turn or a small price negotiation. If comps top out at $2,400, it doesn’t.
Downside case: now apply the earlier stress test — a 10% rent cut and two extra months of vacancy. Cash flow moves further negative. A deal that’s already underwater in the base case has no room left in a downturn; that’s the signal to renegotiate the price, walk away, or find a way to add rentable square footage (an ADU, a legal room addition) that changes the underlying math.
Run this same expense stack on any listing using Calclandlord’s cash flow and cap rate calculators — plug in the real numbers rather than the seller’s optimistic pro forma, which almost always understates expenses.
Financing Your First (and Next) Rental
The right financing route is decided by facts about you, not the property.
| Loan Type | Down Payment | Qualifies On | Best For |
| Conventional investment loan | 20–25% | Your personal income and DTI | First 1–4 properties |
| DSCR loan | Typically 20–25% | The property’s own income | Scaling past what your personal DTI allows |
| House hacking (e.g., FHA) | As low as 3.5–5% | Owner-occupant guidelines | First property, willing to live in it |
| Creative financing (seller financing, subject-to, wraps) | Negotiable | Deal-specific | Situations where conventional debt is unavailable or too costly |
Conventional Investment Loans
Typically 20–25% down with full income documentation and rates above owner-occupied pricing. Because your personal DTI is the constraint, conventional financing tends to stop scaling after a handful of properties.
DSCR Loans
These qualify on the property’s income rather than yours. They’re more expensive than conventional debt but don’t consume your personal DTI, which makes them the standard tool once you’re scaling past a few doors.
House Hacking Financing
Owner-occupant programs like FHA allow far lower down payments in exchange for living in the property yourself, at least initially.
Creative Options
Seller financing, subject-to deals, and wraparound mortgages can work when conventional debt is unavailable or priced too high. These aren’t beginner tools, but knowing they exist expands what you can consider later.
Offer, Close, and Protect Yourself
Price isn’t the only term that decides what a property actually costs you.
Five terms besides price that change your true cost:
- Closing timeline and possession date
- Repair credits vs. straight price reductions
- Appraisal and financing contingencies
- Inspection scope and remedy options
- Earnest money amount and release conditions
Use inspection, appraisal, and financing contingencies to avoid overpaying or inheriting hidden defects — waiving them to win a bidding war shifts real risk onto you.
LLC vs. insurance: You don’t need an LLC for your first property, and forming one can complicate conventional financing. Strong landlord insurance is essential regardless of entity structure; revisit the LLC question as your equity and portfolio size grow, ideally with an attorney familiar with your state’s rules.
Landlord Operations That Protect Returns
Whether you self-manage or hire a property manager, the same operational levers determine your outcomes.
Tenant Screening Scorecard
- Verify income at roughly 3x rent
- Check eviction history and credit
- Call the previous landlord, not the current one (current landlords sometimes just want a problem tenant to leave)
One bad tenancy — unpaid rent, property damage, a slow eviction — can erase several years of cash flow from a single unit.
Maintenance: Scheduled vs. Deferred
Deferred maintenance compounds. A small roof leak ignored for a season becomes a roof replacement plus interior drywall and mold remediation. A common rule of thumb is budgeting around 1% of property value annually for repairs.
Documentation
Use written leases, move-in condition reports with photos, and a running log of every maintenance request and repair. Landlord-tenant law is state-specific — and largely unforgiving of undocumented claims in a dispute. Check your state’s rules through your state government’s housing or attorney general site, and see the CFPB for federal tenant-facing rules like security deposit and credit reporting protections that intersect with landlord obligations.
Self-Manage vs. Hire a Property Manager
Property managers typically charge 8–12% of collected rent, but can reduce vacancy, improve tenant quality, and lower repair costs through existing vendor relationships. Many investors self-manage their first property or two to learn the business, then hand off management as the portfolio grows.
Taxes, Depreciation, and Advanced Optimization
Real estate’s tax treatment is a genuine return that beginners often ignore entirely.
Deductions and depreciation: You can deduct mortgage interest, property taxes, insurance, repairs, and management fees, and depreciate residential property over 27.5 years to shelter rental income. Eligible taxpayers may also qualify for the QBI deduction on qualified rental income, and more advanced investors sometimes use cost segregation studies to accelerate depreciation on specific components of a property.
1031 exchanges: When you sell an investment property, a 1031 exchange can defer capital gains tax by rolling the proceeds into another qualifying property. Some investors use this repeatedly to exchange into larger properties throughout their career.
None of this is a substitute for a CPA who knows your state’s rules — depreciation, QBI eligibility, and exchange timelines all have specific requirements that are easy to get wrong. Confirm current rules at irs.gov.
Risk Management and Scaling
Reserves rule: Keep 3–6 months of full expenses per property. Reserves are the difference between a bad quarter and a forced sale at the worst possible time.
Over-leverage, distance, and concentration: Maximum leverage maximizes returns in good conditions and maximizes insolvency risk in bad ones. Out-of-state investing works, but it requires a trusted local team — agent, property manager, and contractor — before you buy, not after something breaks.
Scaling roadmap:
- Refinance or use a HELOC to recycle equity from existing properties
- Ladder into DSCR loans to preserve your personal DTI for future deals
- Build a repeatable team: agent, lender, property manager, contractors, CPA
Common Mistakes That Sink Beginners
- Underwriting on future appreciation instead of today’s numbers
- Omitting capex and vacancy — the two line items that turn “positive cash flow” negative once real life happens
- Buying at a distance with no local team in place
- Over-leveraging and keeping no reserves
- Treating rentals as passive income when they’re a business with a long feedback loop
Frequently Asked Questions
How much money do I need to start investing in rental property? With conventional financing, plan on 20–25% down plus closing costs and 3–6 months of reserves per property. House hacking can lower the required down payment substantially, sometimes to single digits.
What credit score is needed to buy a rental property? 680+ is generally required by most lenders; 720+ typically secures the best available rates.
What cash-on-cash return should I target? There’s no universal target. What matters more is setting a floor that beats your realistic alternatives after honest expenses — and confirming the deal still clears that floor in a downside case, not just the base case.
Is now a good time to buy rental property in 2026? Rate environments and insurance costs change; the underwriting discipline doesn’t. A deal that works on today’s actual financing, with honest expenses and a real downside case, is a deal worth pursuing regardless of the broader market narrative.
Do I need an LLC for my first rental property? Not necessarily. It’s not required to start, and forming one can complicate conventional financing. Revisit the question with an attorney as your portfolio and equity grow.
Should my first rental be local or out of state? Usually local. Your existing market knowledge and network are real advantages when you have no track record yet. Consider investing out of state only once you’ve confirmed your local market genuinely doesn’t work for your goals — and you’ve lined up a trusted local team first.
People Also Ask
Cash flow is what’s left after all expenses and the mortgage — the number that hits your bank account. Cap rate is NOI ÷ purchase price, ignoring financing entirely, so it’s used to compare deals on an apples-to-apples basis regardless of how each is financed.
A DSCR loan qualifies you based on the property’s own income (NOI ÷ debt service) instead of your personal income or DTI. Lenders typically want a DSCR of 1.20–1.25+, and it’s the standard tool once conventional financing runs out of room.
Yes, for beginners with limited capital — owner-occupant financing (like FHA) allows down payments as low as 3.5–5%, far below standard investment loans. The trade-off is you live in the property, at least at first.
Budget 5–10% of rent for routine maintenance, plus another 5–10% for a separate capex reserve (roof, HVAC, water heater). Older properties trend toward the higher end.
Typically 8–12% of collected rent, sometimes plus a leasing fee. Even self-managing investors should model this cost into their numbers, since it reflects the true cost of the labor even when you’re doing it yourself.
A quick screening rule: monthly rent should be at least 1% of the purchase price (e.g., $3,000/month on a $300,000 property). It’s a rough filter, not a substitute for full underwriting — many solid deals in expensive markets don’t hit it.
Yes. Conventional lenders typically count around 75% of projected or existing lease rent toward your qualifying income. DSCR loans go further, qualifying on the property’s income alone.
Conclusion
Rental property investing rewards discipline, not optimism. The four returns — cash flow, principal paydown, appreciation, and tax treatment — only work in your favor when you underwrite honestly: real expenses, real vacancy, a real downside case. In 2026, with rates and insurance costs higher than a few years ago, that discipline matters more than ever.
You don’t need a perfect first deal. You need one that clears its numbers in a bad year, not just a good one, financed in a way that fits your situation, and managed with systems — screening, maintenance, documentation — that protect the return once the lease is signed.
Use the Calculator

Pingback: 7 Secrets to Maximize Real Estate ROI & Returns
Pingback: Cap Rate Explained: 7 Mistakes Killing Your Returns
Pingback: Property Appreciation: The 1 Formula Landlords Miss
Pingback: BRRRR Strategy: 5 Proven Steps to Escape the Rent Race