How to Fill Out Schedule E for Rental Property: A Complete Landlord Guide
Filing taxes as a rental property owner can be confusing, especially when you’re unsure which income to report, which expenses qualify for deductions, or how depreciation affects your tax return. That’s where Schedule E for rental property becomes essential. Whether you own a single-family rental, manage multiple properties, or rent out a vacation home, understanding this form can help you organize your finances and report rental activity correctly. But small mistakes involving mortgage interest, repairs, security deposits, and rental losses can create problems. In this guide, you’ll learn how to complete Schedule E step by step and avoid common landlord tax mistakes.
Quick answer: How do you fill out Schedule E for rental property?
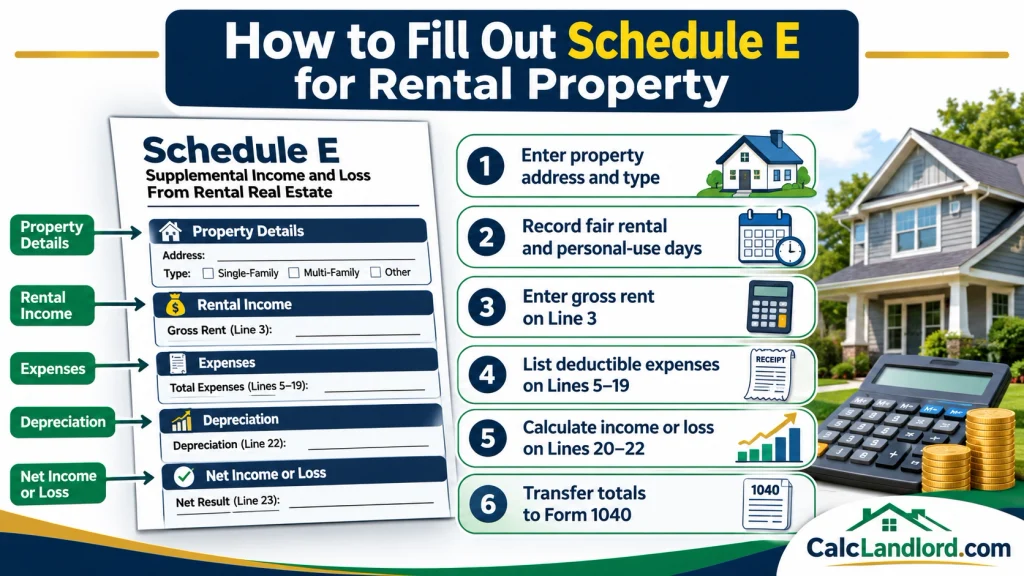
Use Part I of Schedule E (Form 1040) to report rental real estate income and expenses. Enter property details on lines 1a–1b, rental and personal-use days on line 2, rental income on line 3, and allowable expenses on lines 5–19. Calculate expenses and rental income or loss on the subsequent lines, then apply any applicable loss limitations and transfer the appropriate result to your federal tax return.
1. What Is Schedule E and Why Do Rental Property Owners Use It?
Schedule E (Form 1040), Supplemental Income and Loss, is a federal tax schedule used to report income and losses from several sources, including rental real estate, royalties, partnerships, and S corporations.
For most individual landlords, Part I is the important section because it covers rental real estate income and expenses.
Internal Revenue Service+1
Who should use Schedule E?
You will generally use Schedule E Part I if you own rental real estate and collect rent while providing ordinary landlord services.
Examples include:
- A single-family house rented to a long-term tenant.
- A duplex or triplex generating monthly rental income.
- A multifamily apartment building.
- A condominium rented to tenants.
- A vacation property that qualifies for Schedule E reporting.
- Commercial real estate rented under arrangements that qualify for Schedule E.
Example: Suppose you own a duplex in Texas. One unit generates $1,400 monthly, and the second generates $1,600 monthly.
Your annual gross rental income is:
\[ (\$1,400+\$1,600)\times12=\$36,000 \]
You generally report this rental income on Schedule E, with expenses allocated to the appropriate property or rental activity.
What is the difference between Schedule E and Form 1040?
Form 1040 is your individual federal income tax return. Schedule E provides supporting information about rental and other supplemental income.
Schedule E does not replace Form 1040. It helps calculate amounts that flow into your overall federal tax return.
Does every landlord need Schedule E?
No. Your reporting method depends on the nature of your rental activity.
For example, landlords providing substantial services primarily for tenants’ convenience may need Schedule C instead. Certain farm rental arrangements may require Form 4835.
Review the IRS instructions before choosing a form.
Internal Revenue Service+1
2. What Documents Should You Gather Before Completing Schedule E?
The easiest way to complete Schedule E accurately is to organize your financial records before opening the tax form.
Instead of searching through bank statements, receipts, and invoices while filing, prepare a separate financial summary for each property.
Rental income records
Collect:
- Monthly rent payment records.
- Bank statements showing rental deposits.
- Rental platform statements.
- Advance rent receipts.
- Late fee records.
- Forfeited security deposits.
- Records of tenant-paid expenses.
- Documentation of noncash rental payments.
Rental expense records
Organize the following:
| Record | Why it matters |
| Form 1098 | Identifies mortgage interest |
| Property tax statements | Supports deductible property taxes |
| Insurance statements | Documents rental insurance costs |
| Repair invoices | Supports repair deductions |
| Utility bills | Identifies landlord-paid utilities |
| Management invoices | Documents property management fees |
| Advertising receipts | Supports rental marketing expenses |
| Legal and accounting invoices | Documents professional fees |
| Mileage records | Supports qualifying rental travel |
| Depreciation schedule | Supports annual depreciation |
Property ownership records
You should also retain:
- Original purchase agreement.
- Closing disclosure or settlement statement.
- Property purchase price allocation.
- Land and building valuation.
- Improvement invoices.
- Previous depreciation schedules.
- Prior-year Schedule E forms.
These records become particularly important when calculating depreciation or determining the tax treatment of major renovations.
Create a separate expense tracker for each rental
For example:
| Expense category | Property A | Property B |
| Advertising | $200 | $150 |
| Insurance | $1,200 | $1,450 |
| Repairs | $850 | $1,100 |
| Property taxes | $2,500 | $3,100 |
| Mortgage interest | $6,000 | $7,200 |
| Management | $1,800 | $2,000 |
This organization makes it easier to transfer the correct figures into the appropriate Schedule E columns.
The IRS emphasizes maintaining records that substantiate income and deductions.
Internal Revenue Service+1
3. How to Complete Schedule E Property Details on Lines 1a, 1b, and 2
Before reporting rental income or expenses, identify each rental property correctly.
Schedule E Part I contains three property columns: A, B, and C. Each column represents a separate rental property.
Line 1a: Enter the property address
Enter the address of each rental property.
For example:
- Column A: 125 Oak Street, Dallas, TX 75201.
- Column B: 480 Pine Avenue, Houston, TX 77002.
- Column C: 90 Lake Road, Austin, TX 78701.
Use the actual property address, including the city, state, and ZIP code.
Line 1b: Select the property type
The 2025 Schedule E instructions provide these property-type codes:
| Code | Property type |
| 1 | Single-family residence |
| 2 | Multi-family residence |
| 3 | Vacation or short-term rental |
| 4 | Commercial |
| 5 | Land |
| 6 | Royalties |
| 7 | Self-rental |
| 8 | Other |
Choose the code that accurately describes the property.
For example, if you rent out a single-family home, use code 1. If you own a multifamily apartment property, use code 2.
Internal Revenue Service
Line 2: Report fair-rental and personal-use days
This section is particularly important for landlords who rent vacation homes or properties that they occasionally use themselves.
You must distinguish between:
- Fair-rental days: Days the property was rented at a fair market rental price.
- Personal-use days: Days the property was used for personal purposes under the IRS rules.
Example:
Suppose you own a vacation home and rent it during the year.
| Activity | Days |
| Fair-rental days | 180 |
| Personal-use days | 20 |
| Other vacant days | 165 |
You should not automatically treat vacant days as personal-use days.
The IRS has specific rules for determining personal use, including certain family stays and below-market rentals.
If personal use exceeds the greater of 14 days or 10% of fair-rental days, the dwelling may be treated as a home for applicable rental expense limitation purposes.
Internal Revenue Service+1
Landlord tip: Maintain a calendar showing tenant occupancy, personal visits, maintenance work, and periods when the property was available for rent.
4. How to Report Rental Income on Schedule E Line 3
Line 3 is where landlords report gross rental income for each property.
The amount should reflect the rental income received or treated as received under applicable tax rules, not simply the amount of cash remaining after expenses.
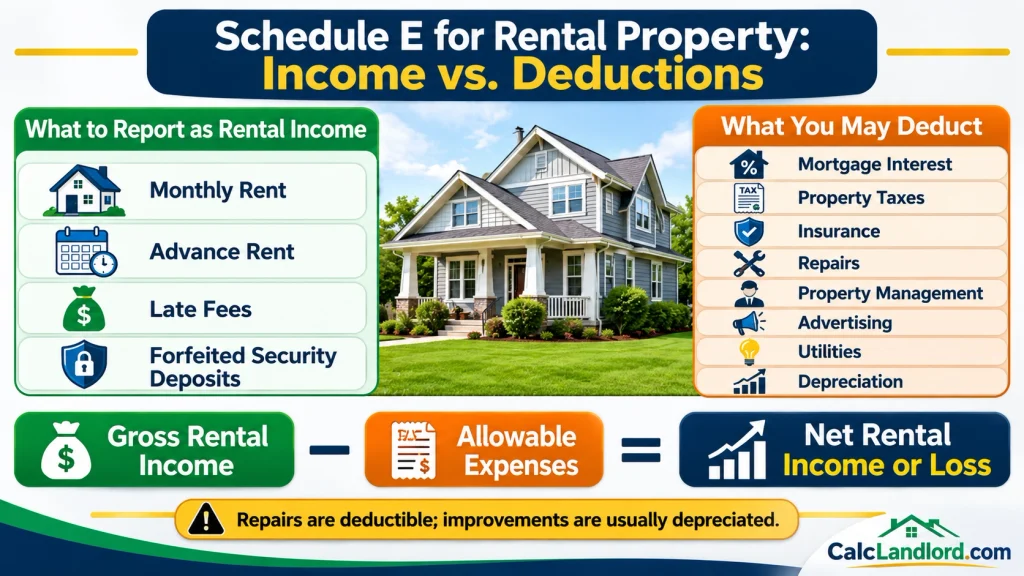
What counts as rental income?
Common examples include:
- Monthly rent payments.
- Advance rent.
- Certain late fees.
- Nonrefundable tenant payments.
- Security deposits retained as payment for rent or damages when the applicable tax rules require inclusion.
- Fair market value of services or property received instead of cash rent.
What about refundable security deposits?
A refundable security deposit that you are holding for return to the tenant is generally not rental income when received.
However, if you later keep the deposit because the tenant owes rent or the applicable rules otherwise require income recognition, the tax treatment changes.
What if a tenant pays rent in advance?
Advance rent is generally rental income in the year received, even if the payment covers a later rental period.
For example, if a tenant pays $3,000 in December for January, February, and March rent, the advance payment is generally included in rental income for December’s tax year.
Worked rental income example
Imagine a landlord receives:
| Income source | Amount |
| Monthly rent | $24,000 |
| Late fees | $300 |
| Advance rent | $1,200 |
| Total rental income | $25,500 |
Assuming these amounts are taxable rental receipts, the landlord reports $25,500 on line 3.
Do not subtract mortgage payments, insurance, repairs, or management fees before reporting gross rent.
Those expenses are reported separately in their appropriate categories.
The IRS specifically addresses rental receipts, advance rent, noncash payments, and retained deposits in its rental income guidance.
Internal Revenue Service+2
5. How to Complete Schedule E Lines 5–19: Rental Expense Deductions
After reporting rental income, the next step is to identify allowable rental expenses.
These expenses generally must be ordinary and necessary for managing, maintaining, or operating the rental activity.
You cannot automatically deduct every payment connected to owning a property. Personal expenses, mortgage principal, and capital improvements require different treatment.
Schedule E rental expense line-by-line guide
| Line | Expense category | Common examples |
| 5 | Advertising | Rental listings and advertising fees |
| 6 | Auto and travel | Qualifying property-management mileage and travel |
| 7 | Cleaning and maintenance | Turnover cleaning and lawn care |
| 8 | Commissions | Leasing-agent commissions |
| 9 | Insurance | Landlord and property insurance |
| 10 | Legal and professional fees | Tax preparation and qualifying legal services |
| 11 | Management fees | Property manager payments |
| 12 | Mortgage interest | Deductible mortgage interest |
| 13 | Other interest | Qualifying rental-related loan interest |
| 14 | Repairs | Fixing broken locks or leaking faucets |
| 15 | Supplies | Consumables used for rental operations |
| 16 | Taxes | Deductible property-related taxes |
| 17 | Utilities | Landlord-paid water, electricity, and gas |
| 18 | Depreciation | Allowable depreciation expense |
| 19 | Other | Other eligible rental expenses |
Internal Revenue Service+2
Understand mortgage interest versus principal
This is an important distinction for landlords.
Suppose your monthly mortgage payment is $1,500:
- Mortgage interest: $950.
- Mortgage principal: $550.
The potentially deductible mortgage interest belongs on line 12, subject to applicable rules.
The $550 principal repayment is not a current rental expense.
Which expenses should landlords track carefully?
Pay particular attention to:
- Property insurance.
- Property taxes.
- Mortgage interest.
- Maintenance and repairs.
- Property management.
- Utility payments.
- Depreciation.
- Advertising and leasing fees.
Important: Do not deduct the value of your own labor. Also, do not automatically classify major property improvements as current-year repairs.
Internal Revenue Service
6. Repairs vs. Capital Improvements: What Can Landlords Deduct?
One of the most important tax distinctions for rental property owners is the difference between a repair and a capital improvement.
A repair generally maintains or restores property to ordinary operating condition. An improvement generally betters the property, restores it, or adapts it to a new or different use.
The tax treatment can be very different.
Repairs versus improvements
| Expense | Typical classification | General treatment |
| Fixing a leaking faucet | Repair | Potential current deduction |
| Replacing a broken window pane | Repair | Potential current deduction |
| Patching a small drywall hole | Repair | Potential current deduction |
| Replacing an entire roof | Improvement | Generally capitalize and depreciate |
| Major kitchen renovation | Improvement | Generally capitalize and depreciate |
| Adding a new room | Improvement | Generally capitalize and depreciate |
| Replacing an entire HVAC system | Improvement | Generally capitalize and depreciate |
The exact classification depends on the facts, applicable tax regulations, and possible safe-harbor elections.
Internal Revenue Service+1
Example: Repair or improvement?
Suppose you own a rental house and experience two separate expenses:
- Repairing a leaking bathroom pipe: $450.
- Replacing the entire plumbing system: $8,000.
The $450 repair may qualify as a current deduction.
The $8,000 plumbing replacement will generally need to be capitalized and recovered through depreciation.
You should not classify the second expense as an ordinary repair simply because the property needed functioning plumbing.
Why does this matter financially?
Suppose you incorrectly deduct a $10,000 capital improvement immediately.
You may overstate current-year deductions and understate the property’s depreciable basis.
Correct classification helps maintain accurate tax records and reduces the risk of reporting errors.
Practical recommendation: Ask your tax professional to review large renovation invoices, roof replacements, HVAC projects, and major structural work before categorizing them on Schedule E.
7. How to Report Rental Property Depreciation on Schedule E Line 18
Depreciation allows eligible rental property owners to recover the cost or other depreciable basis of certain assets over their applicable recovery periods.
It is especially important because depreciation is generally a noncash expense: you may claim an allowable deduction without making an equivalent cash payment during that year.
What is rental property depreciation?
Suppose you purchase a residential rental property for $300,000.
The purchase price includes:
- Land value: $60,000.
- Building value: $240,000.
Land is not depreciable, but the qualifying residential building generally has a 27.5-year recovery period under the general MACRS rules.
For a simplified full-year straight-line illustration:
Annualdepreciation=DepreciablebasisRecoveryperiod
\[ =\frac{\$240,000}{27.5} \]
\[ =\$8,727.27 \]
Illustrative annual amount: $8,727.27
This assumes the building has a $240,000 depreciable basis, is eligible for the general residential rental property treatment, and the example ignores first-year and other adjustments.
Actual depreciation depends on the placed-in-service date, applicable convention, adjusted basis, and other tax rules.
Where does depreciation go on Schedule E?
Report the applicable depreciation expense on line 18 for the relevant property.
Form 4562 may be required, including when you claim depreciation on property first placed in service during the tax year or certain other depreciation deductions.
Internal Revenue Service+1
What about appliances and improvements?
Not every asset follows the residential building’s 27.5-year recovery period.
For example, certain appliances, furniture, and equipment may have different recovery periods.
A qualified tax professional can help separate the building, land, appliances, and capital improvements into the correct tax categories.
Use a depreciation calculator.
The CalcLandlord Depreciation Calculator can be recommended as a starting point for understanding the annual depreciation calculation.
Before relying on an estimate, verify the depreciable basis, recovery period, placed-in-service date, and any special depreciation rules.
Do not assume the purchase price of the entire property is depreciable.
8. How to Calculate Rental Income or Loss on Schedule E Lines 20–22
After entering allowable rental income and expenses, you can determine whether your property generated taxable rental income or a rental loss before applicable limitations.
The basic calculation is:
Rentalincomeorloss=Grossrentalincome-Totalallowableexpenses
What happens on line 20?
Line 20 reports total rental expenses for the applicable property column.
This includes the relevant expenses entered on lines 5–19.
What happens on line 21?
Line 21 calculates the property’s income or loss by subtracting total expenses from income.
What happens on line 22?
Line 22 reflects the rental real estate loss allowed after applicable limitations, when those rules apply.
If a loss is limited, Form 8582 may be necessary.
Example: Calculate annual rental income
Suppose you own a single-family rental property.
| Income and expenses | Annual amount |
| Gross rental income | $30,000 |
| Advertising | $300 |
| Insurance | $1,400 |
| Repairs | $1,000 |
| Property taxes | $3,200 |
| Mortgage interest | $8,000 |
| Management fees | $2,400 |
| Utilities | $700 |
| Depreciation | $8,000 |
| Total expenses | $25,000 |
Calculation:
\[ \$30,000-\$25,000=\$5,000 \]
Illustrative net rental income
$5,000
Before considering any other applicable tax adjustments or limitations.
The example demonstrates the reporting calculation, not the property’s actual cash flow or final tax liability.
Why rental income and cash flow are different
A landlord might report positive rental income while experiencing lower cash flow because of mortgage principal payments or other cash expenditures that are not current Schedule E deductions.
For example:
- Net rental income: $5,000.
- Mortgage principal paid: $4,000.
- Additional capital improvement: $2,000.
Cash remaining after these two cash expenditures would be:
\[ \$5,000-\$4,000-\$2,000=-\$1,000 \]
This simplified illustration shows why tax profit and actual cash flow should not be treated as identical measurements.
A rental property cash flow calculator can help investors evaluate the operational side separately.
9. How Do Passive Activity Loss Rules Affect Schedule E?
A rental property can generate a tax loss even when the landlord collects rent throughout the year.
However, that does not automatically mean the entire loss can reduce wages, business income, or other nonpassive income.
Many rental real estate activities are treated as passive activities under federal tax rules.
What is a passive rental loss?
A passive rental loss generally occurs when allowable rental deductions exceed the income from the activity, subject to the applicable tax limitations.
The IRS may restrict how much of that loss you can deduct in the current year.
Can landlords deduct up to $25,000 in rental losses?
Certain landlords who actively participate in rental real estate may qualify for a special allowance of up to $25,000.
However, the allowance is subject to eligibility requirements and income-based phaseout rules.
For 2025, the general phaseout begins when modified adjusted gross income exceeds $100,000 for many eligible taxpayers and is generally fully phased out at $150,000. Different limits apply to certain married taxpayers filing separately.
Internal Revenue Service+1
Example: How the special allowance can work
Suppose a qualifying landlord:
- Has modified adjusted gross income of $80,000.
- Actively participates in rental management.
- Has an eligible rental real estate loss of $12,000.
- Meets the other requirements.
The landlord may qualify to deduct the $12,000 loss against nonpassive income under the special allowance.
This is not an automatic deduction for every landlord. Other passive activities, ownership requirements, prior-year losses, and other limitations must be considered.
What if the loss cannot be deducted?
An otherwise allowable passive loss that is disallowed generally carries forward and may become deductible in a future year when applicable rules permit.
Form 8582 helps determine the amount of passive activity loss that can be deducted.
- Explore More: https://calclandlord.com/how-to-rent-out-a-duplex/
What is the real estate professional exception?
Certain taxpayers who meet the IRS real estate professional tests and materially participate in their rental activities may be able to treat those rental activities as nonpassive.
Generally, the tests include:
- More than half of the individual’s personal services in all trades or businesses being performed in real property trades or businesses in which the individual materially participates.
- More than 750 hours of services during the tax year in those qualifying real property trades or businesses.
These requirements are technical, and qualifying as a real estate professional does not automatically make every rental loss deductible.
Internal Revenue Service+1
10. How to Complete Schedule E When You Own More Than Three Rental Properties
Owning several rental properties does not mean you must squeeze every property into one column.
Schedule E Part I has three property columns: A, B, and C.
You can use additional Schedule E forms when you own more than three rental or royalty properties.
How the multiple-property rule works
| Number of properties | Reporting approach |
| 1 | One property column |
| 2 | Two property columns |
| 3 | Three property columns |
| 4 | Additional Schedule E required |
| 5–6 | Additional columns on attached schedules |
| More than 6 | Continue using additional schedules as needed |
The important rule is that lines A and B and the combined totals on lines 23a–26 should be completed on only one Schedule E.
The additional forms provide the property-level information, while the designated form contains the combined totals.
Internal Revenue Service+1
Example: A landlord with five properties
Imagine an investor owns:
- A single-family rental in Florida.
- A duplex in Georgia.
- A condominium in Texas.
- A rental house in Ohio.
- A small apartment property in Arizona.
The first three properties can be entered in columns A, B, and C of the first Schedule E.
The remaining two properties go on another Schedule E.
You must keep each property’s rental income and expenses separately identifiable.
What if you own only part of a rental property?
If you own a partial interest in a rental property, the IRS generally requires you to report your share of the rental income and expenses.
For example, if you own a qualifying 50% interest in a jointly owned rental activity, your reported amounts generally reflect your share, subject to the applicable ownership and tax-reporting arrangements.
Co-ownership, partnerships, community property, and qualified joint ventures can create additional requirements.
Do not assume every co-owned property should be reported in the same way.
11. Schedule E vs. Schedule C: Which Form Should Airbnb and Short-Term Rental Owners Use?
Not every property rental activity belongs on Schedule E.
The distinction between Schedule E and Schedule C is especially important for vacation rentals and short-term rental businesses.
The IRS generally uses the nature of the services provided to determine the appropriate reporting treatment.
Schedule E versus Schedule C
| Factor | Schedule E | Schedule C |
| Typical activity | Traditional rental real estate | Business activity |
| Services | Basic landlord services | Substantial tenant-convenience services |
| Example | Long-term residential rental | Qualifying rental activity with substantial services |
| Reporting | Supplemental income and loss | Profit or loss from business |
Internal Revenue Service+2
When might Schedule E apply to Airbnb?
Suppose you rent out a furnished vacation apartment.
You provide:
- Electricity and water.
- Heating and air conditioning.
- Trash collection.
- Cleaning of common areas.
These basic services do not automatically make the rental a Schedule C activity.
When might Schedule C apply?
Consider a short-term rental where the owner provides substantial services primarily for guests’ convenience, such as:
- Regular maid service during stays.
- Frequent linen changes.
- Hotel-like guest services.
- Other substantial personal services.
The IRS may require Schedule C reporting when significant services are provided.
What should short-term rental owners check?
Before filing, examine:
- Average rental period.
- Services offered to guests.
- Frequency of cleaning.
- Whether services are primarily for guest convenience.
- Whether the activity qualifies for an exception under passive activity rules.
- Whether additional business or lodging tax requirements apply.
Short-term rental taxation can involve additional state and local rules, so professional tax guidance is especially valuable.
12. How Do Personal-Use Days and Partial-Year Rentals Affect Schedule E?
A rental property does not always operate as a full-time rental throughout the tax year.
You might purchase a property in June, sell it in October, use it personally during part of the year, or convert your former residence into a rental.
These circumstances can affect how income and expenses are allocated.
Scenario 1: You start renting halfway through the year
Suppose you purchase a property in January but do not make it ready and available for rent until July.
Your rental activity generally begins when the property is ready and available for rent, rather than automatically on the purchase date.
You must properly identify the rental period, placed-in-service date, and eligible expenses.
Scenario 2: You use your vacation rental personally
Suppose you rent a vacation property for 100 days and use it personally for 20 days.
The 20 personal-use days may affect whether the property is treated as a home for tax purposes.
The IRS personal-use threshold is generally the greater of 14 days or 10% of the fair-rental days.
For 100 fair-rental days:
\[ 100\times10\%=10\text{ days} \]
The greater amount is 14 days.
Since personal use is 20 days, the property exceeds the threshold.
The applicable vacation-home expense allocation and loss rules must then be considered.
Internal Revenue Service+1
Scenario 3: You rent out only part of your home
Suppose you live in a house and rent one bedroom to a tenant.
You generally need to allocate shared expenses between the rental and personal portions using an appropriate method.
For example, if the rental portion represents 25% of the home’s applicable area, some shared expenses may be allocated using that percentage, provided it is reasonable for the expense involved.
Do not automatically deduct 100% of household expenses when only part of the property generates rental income.
Practical advice
Maintain separate records for:
- Rental dates.
- Personal-use dates.
- Vacancy periods.
- Property preparation.
- Maintenance.
- Property conversion.
- Sale or disposal dates.
Accurate dates help support the reporting and depreciation calculations.
13. What Are the Most Common Schedule E Mistakes Landlords Should Avoid?
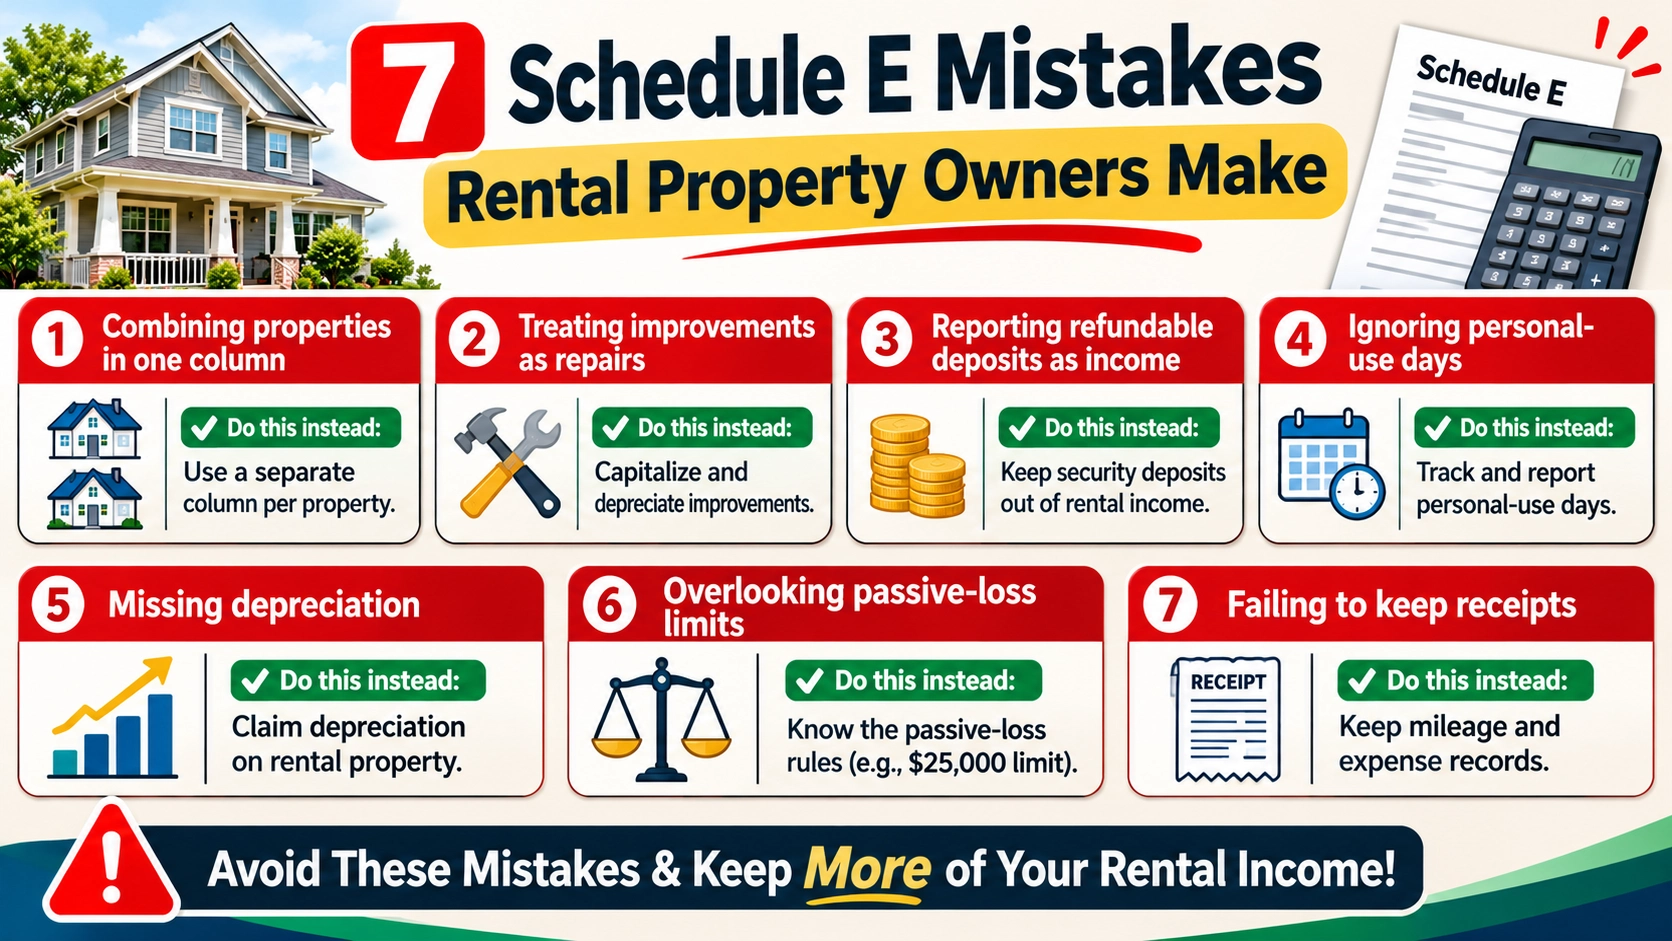
Even experienced rental property owners can make reporting mistakes when records are incomplete, or expenses are incorrectly categorized.
The following errors deserve particular attention.
Mistake 1: Reporting net rent instead of gross rent
Do not subtract operating expenses before reporting rental income on line 3.
Report income and eligible expenses separately.
Mistake 2: Deducting mortgage principal
Mortgage principal repayment is not the same as deductible mortgage interest.
Use your mortgage statement to identify the interest component.
Mistake 3: Treating every renovation as a repair
A new roof or major renovation may need to be capitalized rather than deducted immediately.
Mistake 4: Forgetting depreciation
Eligible rental property owners must account for depreciation under applicable tax rules.
Failing to maintain accurate depreciation records can create problems when selling the property.
Mistake 5: Reporting refundable deposits as rental income
A refundable deposit is generally not rental income when received, although later retention can change its treatment.
Mistake 6: Ignoring personal-use days
Vacation rentals require careful day-count records.
Mistake 7: Assuming all rental losses are immediately deductible
Passive activity rules may limit the amount you can deduct.
Mistake 8: Combining multiple properties incorrectly
Each property should have separately identifiable income and expenses.
Mistake 9: Forgetting local tax requirements
Federal Schedule E reporting does not automatically satisfy state or local tax obligations.
Mistake 10: Failing to retain supporting documentation
Keep invoices, receipts, bank statements, closing documents, depreciation schedules, and relevant tax forms.
A practical pre-filing checklist
- Verify rental income for every property.
- Check refundable and retained security deposits.
- Reconcile rent with bank statements.
- Separate mortgage interest from principal.
- Review repair and improvement classifications.
- Verify property tax and insurance expenses.
- Calculate eligible depreciation.
- Confirm fair-rental and personal-use days.
- Review passive activity loss limitations.
- Verify totals across additional Schedule E forms.
- Retain supporting documents.
14. What Happens After You Complete Schedule E Lines 23–26?
Completing the individual property columns is not the final step.
You must also review the summary section to determine the combined rental real estate income or loss and the amount that carries into your individual tax return.
Understanding the Schedule E summary
The relevant summary lines include:
| Line | Purpose |
| 23a | Total rents received |
| 23b | Total royalty payments received |
| 23c | Total mortgage interest |
| 23d | Total depreciation and depletion |
| 23e | Total expenses |
| 24 | Income or loss from rental real estate |
| 25 | Income or loss from royalties |
| 26 | Total rental real estate and royalty income or loss |
Internal Revenue Service+1
Where does Schedule E income go on Form 1040?
For a taxpayer whose only Schedule E activity is rental real estate reported in Part I, the result generally flows through Schedule 1 (Form 1040), line 5, and then into Form 1040.
Other Schedule E activities and additional tax limitations can change the reporting process.
Do not assume line 26 always equals the final deductible rental loss. Passive activity, at-risk, and other applicable rules may affect the amount.
What should you review before filing?
Check that:
- All rental properties have been included.
- The totals agree with the property-level records.
- Depreciation has been calculated correctly.
- The applicable loss limitations have been addressed.
- Additional forms are attached where required.
- Your Schedule 1 and Form 1040 reflect the appropriate amounts.
What about state income taxes?
Schedule E is a federal tax reporting form.
States may have their own income tax rules, depreciation adjustments, reporting requirements, and filing deadlines.
Check the relevant state’s official tax authority before assuming your federal treatment applies identically at the state level.
15. People Also Asked Questions: What Landlords Need to Know
Complete Part I by entering the property address and property type, reporting fair-rental and personal-use days, entering gross rent on line 3, and reporting allowable expenses on lines 5–19. Calculate the resulting income or loss and address applicable limitations.
No. One Schedule E provides three property columns. If you own more than three rental or royalty properties, attach additional schedules and report combined totals on only one Schedule E:
Line 3 reports rental income from real estate, including qualifying advance rent, rental payments, and the fair market value of noncash rental payments.
Generally, qualifying ordinary repairs can be deducted on line 14. Capital improvements usually must be capitalized and recovered through depreciation.
Depreciation and depletion are reported on line 18. Form 4562 may also be required depending on the circumstances.
Conclusion: Build Better Rental Property Tax Records
Filling out Schedule E correctly is about more than entering rent and subtracting expenses. Landlords need to understand how income is classified, which expenses qualify for deductions, when improvements must be depreciated, and how rental losses are treated under federal tax rules.
The most important numbers to verify are:
- Gross rental income reported on line 3.
- Total allowable expenses reported on line 20.
- Depreciation reported on line 18.
- Rental income or loss calculated on line 21.
- Applicable deductible loss limitations reflected in the subsequent calculations.
Key takeaways
- Organize rental income and expenses separately for every property.
- Report gross rental income rather than rent remaining after expenses.
- Separate mortgage interest from mortgage principal.
- Understand repairs versus capital improvements.
- Calculate depreciation using the correct tax basis and recovery period.
- Track personal-use days for vacation rentals.
- Understand passive activity loss limitations.
- Use additional Schedule E forms when reporting more than three properties.
- Keep receipts, invoices, bank statements, and depreciation records.
- Review federal and state tax requirements before filing.
Your next step as a landlord
Before preparing your return, reconcile each property’s annual income and expenses. If you have multiple properties or complicated depreciation and loss situations, have a qualified tax professional review your figures.
